RSS

What Calgary Homeowners Should Know Before Choosing

After several years of rate volatility, mortgage rates in Canada are finally finding balance. As interest rates stabilize, many Calgary buyers and homeowners up for mortgage renewal are asking the same question: Is it better to lock in or stay flexible?

With economists offering mixed signals about what’s next for interest rates and Calgary’s housing market trending toward more balanced conditions, one thing is clear — there’s no single right answer for everyone.

The best mortgage choice for you depends on a combination of intersecting factors, including your personal financial situation, risk appetite, and long-term goals, making it as much a strategic decision as a financial one.

Read on to learn more about current rates, market conditions, and the pros and cons of rate options depending on your unique scenario.

Rates Are Levelling — But So Are the Differences

As of late 2025, the Bank of Canada’s overnight rate sits at 2.50%, following several small but significant cuts — its lowest point since 2022. In Calgary, five-year fixed mortgage rates now average 4.09% to 4.44%, depending on your lender and credit profile, while five-year variable rates are hovering just below fixed rates, at around 3.95% to 4.20%.

This near parity is unusual. Typically, fixed rates carry a premium to reflect future uncertainty, while variable rates are priced lower to entice borrowers willing to take on economic and market risks.

Why are Fixed and Variable Rates So Close?

While the shrinking gap between fixed and variable interest rates can be attributed to several different factors, much of it comes down to stability. In shifting from aggressive tightening to signalling potential cuts, the Bank of Canada has reduced the need for lenders to price in large cushions to accommodate their risk. In other words, when the central bank policy rate holds steady, both fixed and variable products tend to meet in the middle.

Bond markets also play a key role in where mortgage rates land. As fixed rates are tied to government bond yields, the recent dip in yields, fueled by concerns over slower economic growth and easing inflation, has helped bring fixed mortgage rates down.

Meanwhile, variable rates, which move with the Bank of Canada’s prime rate, have held steady due to the central bank being cautious about making deeper cuts, further narrowing the gap between fixed and variable rates.

Fixed-Rate Mortgages: The Case for Predictability

For many homeowners, choosing a fixed-rate mortgage isn’t about finding the absolute lowest rate; it’s about peace of mind. Fixed rates offer predictability, ensuring your payments stay the same for the entire term. That simplifies long-term budgeting and eliminates the stress of wondering what might happen if rates shift again.

This approach is especially appealing for households with limited financial flexibility, those on fixed incomes, or families planning to stay in their homes for several years. Even if rates dip slightly, paying a bit more for stability can feel worthwhile, serving as a kind of insurance against the unexpected.

Fixed rates also offer protection if forecasts turn out to be wrong. Should inflation resurface or global pressures force the Bank of Canada to raise rates again, borrowers locked into fixed terms would be shielded from sudden payment increases. After the rapid hikes of 2022 and 2023, that kind of security feels more valuable than ever.

Pros:

  • You know precisely what you’ll pay each month.

  • Protects you from unexpected rate hikes.

  • Peace of mind — especially if you’re planning to stay in your home long term.

Cons:

  • Often higher than variable rates.

  • Breaking the mortgage early can carry significant penalties.

  • Locked into your rate until the term ends, even if rates drop.

Could Fixed Rates Become Cheaper?

Yes, it’s always possible that fixed rates could drop.

If bond yields were to fall due to economic data or global uncertainty driving investors toward safer assets like government bonds, fixed mortgage rates could drop a little further. A downward shift in yield would give lenders more room to lower fixed rates in a meaningful way.

That said, most forecasts still suggest variable mortgages will keep a slight edge through late 2025 and into 2026. However, the gap between the two will likely stay narrow, and the days of variable rates offering a full percentage-point advantage over fixed rates are probably behind us for the foreseeable future.

Variable-Rate Mortgages: The Case for Flexibility

A variable-rate mortgage moves with the Bank of Canada’s policy rate, meaning your payments can fluctuate. Variable mortgages come in two main types:

  1. Adjustable-rate (ARM): Your payment changes as rates move. When rates drop, your payment decreases; when they rise, your payment increases.

  2. Fixed-payment variable: Your payment stays the same, but the balance between principal and interest shifts. When rates drop, you pay down your mortgage faster; when they rise, progress slows — and if rates climb too high, you may hit a trigger point requiring a higher payment or conversion to fixed.

In short, lower rates don’t always mean more monthly cash flow unless you lock in or have an adjustable plan — but they can help you build equity faster.

Plus, beyond rate movements, variables also come with a few structural advantages. The penalties for breaking them are typically much lower than with fixed mortgages — an essential consideration if you plan to move, refinance, or make larger prepayments before your term is up. Most variable products also allow borrowers to convert to a fixed rate mid-term without penalty, providing the flexibility to adapt if conditions change.

Pros:

  • Potential to benefit if rates decline.

  • Easier to pay down or refinance early.

  • Good fit for short- to mid-term ownership plans.

  • Can lock into a fixed rate for the remainder of the term if the fixed rate is lower

  • The payout penalty is usually lower if you discharge the mortgage (i.e., sell the property).

Cons:

  • Rising payments if rates increase.

  • Greater exposure to market volatility.

History Favours the Bold

Looking back historically offers a valuable perspective on variable-rate mortgages. Interestingly, between the 1950s and 2000, Canadian homeowners who chose variable mortgages came out ahead about 90% of the time.

After the 2008 financial crisis, when central banks slashed rates to stimulate growth, variable borrowers again saw meaningful savings. And during the pandemic, variable rates dropped to record lows (in some cases as little as 0.88%) while fixed rates stayed higher due to uncertainty in the bond market.

But history also reminds us of the risks. In 2022 and 2023, variable-rate borrowers felt the sting of the fastest rate hikes in decades. Monthly payments jumped by hundreds of dollars, quickly erasing the advantage variables had offered. That experience remains fresh for many homeowners, making risk tolerance a far more critical part of the mortgage decision than it used to be.

In Summary

As Calgary’s market finds its balance and interest rates begin to steady, the decision between a fixed or variable mortgage isn’t about finding the one “right” answer; it’s about finding the right fit for you.

Choosing a mortgage today requires more than comparing numbers. It means looking honestly at your financial situation, lifestyle, and comfort level with risk. Fixed rates can bring calm and predictability for households that value security, while historically, variable rates have rewarded those with flexibility and a higher tolerance for risk.

What matters most is understanding how each option aligns with your personal goals. Whether you prioritize steady cash flow or the possibility of long-term savings, your mortgage choice should fit your overall financial rhythm — not the other way around.

At the Trung Bien Real Estate Team, we believe good real estate decisions come from a clear strategy, not guesswork.

Thinking about your next move?

Our team can help you evaluate your options, connect with trusted mortgage professionals, and build a plan that’s right for your home, your budget, and your peace of mind. 

Connect with us.


Read

Why Lifestyle (Not Timing) Is the Primary Factor to Consider

There’s a familiar homeownership dream: you’re ready to buy a home now but can’t yet reasonably afford a semi-detached or detached house, so you purchase a new, more affordable condo you can enjoy today, planning to eventually upgrade as values rise.

However, unlike cities such as Toronto and Vancouver, where condo prices have soared over the past decade alongside the broader real estate market, Calgary hasn’t followed that script.

Calgary’s story has been one of slower appreciation with some backpedalling. Compared with other Canadian markets, condo values in our city have been more modest, with occasional dips that take time to correct.

So, if you’re considering purchasing a condo in Calgary, here are some essential, market-specific points to help guide your decision before you buy.

Oversupply Generally Shapes Calgary’s Condo Market

Calgary isn’t short on ambition. Our skyline has grown steadily, like other metropolitan cities, with new towers rising from the Beltline to the East Village. And with the recent surge in international and intraprovincial migration, it would be easy to assume condo prices are likely to steadily rise, as they have in Toronto and Vancouver.

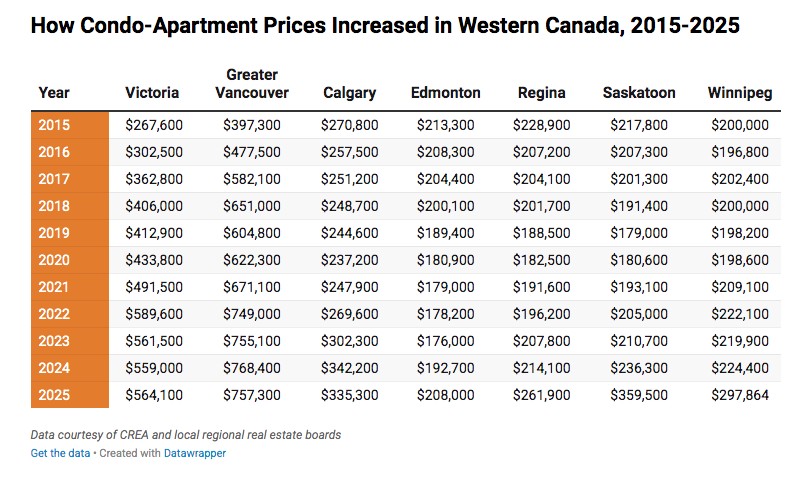
But the numbers tell a different story. From 2021 to 2024, many Calgary condo owners were thrilled to see the median price increase to $342,200 — a nearly $75,000 advance from 2015 (see chart below).

While those numbers may seem encouraging, consider that in Vancouver, during the same period, condo prices increased by almost $400,000.

It’s also worth noting that in the first half of 2025, median condo prices in Calgary decreased by approximately $7,000 to $335,300. This indicates that, although inner-city construction has surged, demand for condos has returned to relatively modest levels, and it’s currently a buyer’s market again for condos in Calgary.


Why?
In addition to record migration rates finally slowing, it’s essential to remember that geographically, Calgary has room to grow as well as the zoning flexibility that allows for continued development of affordable single-family homes on the city’s outskirts.For many buyers — especially young families moving from pricier markets — detached housing in Calgary remains within reach, pulling demand away from condos and reducing the urgency that typically drives condo price appreciation in denser cities.The result is generally high inventory, often stagnant prices (especially in downtown areas), and a slower-moving condo market, particularly for properties without standout features.

So What Does That Mean for Buyers?

The decision to buy—or invest in—a condo in Calgary should be grounded in the realities of our market, not just timing or speculation.

Too often, buyers enter the market thinking, “I’ll get in now, ride the market up, and upgrade later.” But in Calgary, that logic can backfire. With median condo values growing slowly and even declining at times, there’s no guarantee you’ll build the equity needed to trade up or cash out when the time comes.

Over the years, we’ve seen many buyers get stuck: unable to sell without taking a loss, or holding onto a unit longer than planned while waiting for the market to recover. For example, in 2015, the median condo price in Calgary was $270,800. By 2021, it had decreased to $247,900. The average buyer who purchased a condo in 2015 would have had to wait approximately 8 years until 2022/23 for median prices to rise above their purchase price. 

The same caution applies to investors. If your primary goal is appreciation, Calgary’s condo market may not deliver the returns you're hoping for. High inventory, flat pricing, and ongoing competition from newer buildings make it challenging to speculate on price increases or profit from resale.

Lifestyle First: The Real Reason to Buy a Condo in Calgary

Despite the market-specific realities, condos can still be a fantastic option for many people—if they support or enhance your lifestyle goals, not just your financial ones. Rather than chasing appreciation, potential condo buyers should focus on lifestyle fit.

Ask yourself:

  • Do you value walkability and being close to the action?

  • Do you anticipate your family size staying the same for the next 3–5 years?

  • Is low-maintenance living a priority?

  • Do you travel often or want a home you can lock and leave?

If you answered yes to these questions, a Calgary condo could be the right choice.

Find the Right Fit for You

The benefit of having a high-inventory condo market, as we do in Calgary, is that you typically have a wide range of options to choose from, so there’s no need to rush your decision.

We always counsel buyers to take their time. The best condo isn’t always the flashiest — it’s the one that fits your life like a glove. A well-chosen condo offers flexibility, ease, and freedom. Amenities such as concierge service, underground parking, and on-site gyms can genuinely enhance your daily life.

Focus on how the property enhances your day-to-day living. Will it simplify your routine? Offer walkability? Let you downsize with dignity?

It’s helpful to spend significant time in the neighbourhood before buying. Experience the area over a few seasons. Make sure it’s somewhere you’ll thrive, not just tolerate. And remember, not all buildings are equal. 

Be selective:

  • Look for well-managed properties with healthy reserve funds.

  • Choose locations with staying power, not just hype.

  • Understand condo fees and what they cover.

Final Thoughts

Ultimately, buying a condo in Calgary isn’t about trying to time the market. It’s about making a choice that aligns with how you want to live. In a city with more space and more options, clarity around your lifestyle priorities matters more than chasing short-term gains.

Condo ownership can be advantageous when it’s rooted in purpose. When your purchase aligns with your needs, your rhythms, and your future plans, you’ve already made a wise investment, regardless of how the market moves.

Ignore the noise. Skip the speculation. Focus instead on what matters most: your quality of life.

When you buy for lifestyle over timing, you gain peace of mind, everyday comfort, and a home that works for you.

—

Want to chat more about the pros and cons of buying a condo in Calgary’s market?

 📞 Call us today at 403-401-4222

 💬 Or reach out online at www.trungbien.ca


Read

How to Price Your Home Strategically in a Balanced Market

If you’re preparing to sell your home in Calgary, pricing it right becomes more essential as our market shifts into balanced conditions, where supply and demand are relatively equal with fewer multiple-offer scenarios than we’ve seen in recent years.

Today’s market demands clarity, precision, and strategy, and that’s where strategic pricing comes in.

Strategic pricing is more than just picking a number you “hope” to get. It’s a deliberate, data-backed approach that factors in buyer behaviour, comparable sales, local trends, and your home’s unique condition.

When done correctly, strategic pricing helps your property stand out, attract the right buyers, and sell at the best possible price — all without sitting on the market longer than necessary.

Let’s take a look.

Understanding List Price and Sale Price

Before we get into how to price your home, it’s essential to understand the difference between two often-confused terms: list price and sale price.

List price is your home’s asking price: what you publicly market it for. It sets the tone for how buyers perceive your property and determines how it appears in online search criteria based on buyers’ search conditions.

Sale price, on the other hand, is the final agreed-upon amount between buyer and seller after negotiations.

In a balanced market, the gap between list and sale price can reveal a lot about your pricing strategy. If you list too high, you may receive little traffic, sit on the market for extended periods, and ultimately settle for a lower sale price after reductions and prolonged negotiations.

If you list too low, hoping to spark a bidding war (two or more offers in the same time period) or receive multiple offers sequentially in a short period, that strategy may no longer pay off. With fewer multiple-offer situations, you risk selling below market value, especially if the right buyers aren’t watching.

Factors that Influence Strategic Pricing

In a balanced market, buyers are doing their homework. They’re comparing sold prices, looking for value, and skipping over listings that feel inflated. A well-priced home signals transparency, realism, and confidence.

 Strategic pricing is the process of finding that ideal pricing position—not too high, not too low—for current market conditions to make it approachable for an offer.

 Ultimately, the goal of strategic pricing is straightforward: to attract the right buyers early, create momentum, and convert interest into strong offers that result in successful closings. This isn’t guesswork—it’s a formula that weighs some essential factors:

Comparable Sales (Comps) – Start with what has sold, not what’s listed. Look at recent, similar properties that match your home’s size, style, condition, and location whenever possible. The more recent the sale, the better. Remember: buyers are using the same data. If your home is priced significantly above similar properties that just sold, they’ll be advised of that by their Realtor®.

Days on Market (DOM) – Homes that sit on the market too long raise red flags. In a balanced market, buyers assume stale listings are overpriced or flawed in some way. Setting your price too high at the outset often results in fewer showings, followed by price drops, and ultimately, less-than-desirable offers.

Property Condition and Upgrades – Does your home shine, or show its age? Buyers pay more for properties that feel move-in ready. If your home is clean, updated, and staged well, you can push the upper end of your pricing range. If your home needs cosmetic updates or repairs, be realistic: buyers will factor those costs into their offer. Pricing accordingly can help you move the home faster and avoid lengthy negotiations.

Location and Micro-Market Trends – Calgary isn’t a monolithic market. Trends can vary dramatically between apartments and semi-detached or detached homes, as well as between neighbourhoods, depending on factors such as school zones, proximity to transit, upcoming developments, and neighbourhood amenities.

Seller Motivation and Timeline – Your pricing strategy should reflect your goals. If you need to sell quickly due to a relocation, job change, or financial responsibilities, it makes sense to price competitively from the start. If you have flexibility and the home is in top condition, you might explore the upper edge of market value without stretching into wishful thinking.

Strategies for Setting the Right Price

Once you understand the influencing factors, the next step is putting them into practice with proven pricing tactics. Here’s how to price your home smartly and avoid common mistakes:

Work With a Local Real Estate Expert
A seasoned agent understands current buyer behaviour, micro-market trends, and negotiation dynamics. They’ll complete a detailed market evaluation using real sales data — not opinions or outdated comps — and help you interpret the numbers based on your unique situation.

Consider Price Bracketing
Many buyers search using price filters (for example: $700K–$750K). Pricing just below a standard threshold, such as $749,900 instead of $750,000, can place your listing in front of a wider audience and create a psychological impression of better value. At the same time, buyers with a search criteria of $750k+ won’t see your listing. So, the pros and cons of pricing for a particular bracket should always be discussed with your Realtor®.

Incorporate Psychological Pricing
Numbers like $724,900 “feel” more approachable than $700,000 or $725,000. These subtle pricing choices help your listing stand out online and encourage more clicks and showings. However, it's best to use numbers that don’t fall on the bookends of typical search brackets, such as $700k+, and risk being filtered out of a buyer’s search criteria.

Avoid These Common Pricing Pitfalls

  • Overpricing: Setting the price too high is one of the most frequent — and costly — mistakes sellers make. It often results in reduced showings, inevitable price reductions, and ultimately, weaker offers. Some sellers believe that pricing high leaves room for negotiation or invites low-ball offers. But in Calgary’s market, where buyers tend to be respectful and less inclined to submit aggressively low offers, an overpriced home may be quietly passed over entirely.

  • Underpricing Without Strategy: May result in a fast sale, but leaves money on the table, especially if it doesn’t trigger a bidding war.

  • Emotion-Based Pricing: Pricing your home based on what you “need” or what you “put into it” rather than what the market will support is risky. Buyers aren’t paying for your memories—they’re evaluating value.


Final Thoughts: The Right Price Gets You the Best Price

In a balanced market, your pricing strategy sets the tone for everything that follows: marketing, showings, negotiations, and ultimately, your sale price. The most successful sellers don’t chase the market. They lead it with clarity, precision, and insight.

Strategic pricing isn’t about being conservative. It’s about being smart. It positions your home to attract interest, create momentum, and inspire strong offers, all while protecting your bottom line.
Every home and every market is different.

Wondering what your Calgary home is worth? Our team offers a complimentary strategic pricing consultation that includes a detailed market evaluation, local trend insights, and a personalized pricing strategy tailored to your goals.
If you're ready to sell smart in today’s market, our team is ready to help.


📞 Call us today at 403-401-4222
💬 Or reach out online at trungbien.ca

Read

What First-Time Buyers Should Consider in a Balanced 2026 Market

If you’re a first-time buyer in Calgary right now, you’ve likely asked yourself the question more than once: Should I keep renting, or is it finally time to buy?

After several years of sharp price growth, rising interest rates, and intense competition, Calgary’s housing market has shifted into more balanced conditions. Prices have stabilized across many segments, and inventory has increased. As rents remain elevated in many categories and resale prices have stabilized or softened, many renters who felt priced out during the peak years are starting to re-evaluate.

But the rent-versus-buy question has never been just about the market. It is also about personal timing and alignment. Your income stability, risk tolerance, time horizon, and financial discipline matter just as much as market dynamics.

In this month’s blog, we break down what should drive first-time buyers’ decisions in Calgary today.

What Matters More: The Market Headlines or Your Personal Financial Reality?

For first-time buyers, the decision to rent or buy is less about where the market is heading and more about whether ownership strengthens your financial position and aligns with your goals over the next five to ten years.

Market conditions influence opportunity, but personal readiness ultimately determines sustainability.

In real estate conversations, public attention tends to focus on benchmark prices, interest rates, and migration trends. Those forces matter at a macro level. They shape affordability and sentiment. But in practice, we regularly see two buyers with similar incomes make completely different decisions. One may have strong savings discipline and low debt, or even financial assistance toward their down payment. The other may be carrying more consumer obligations or working with minimal cushion in their monthly finances.

The market may look the same to both, but their risk profiles do not. So the better question is not, “Is this a good time to buy?” It is, “Will buying improve my long-term position given my current foundation?”

Is Renting a Financial Mistake or a Strategic Decision?

Renting can be a disciplined and financially intelligent decision when liquidity, flexibility, or stability are still developing. The reality is that home ownership only begins to outperform renting when appreciation and principal repayment exceed transaction costs and carrying expenses over time.

Generally, the breakeven horizon falls in the 4- to 7-year range, depending on interest rates, property type, and appreciation patterns.

During the early years of a mortgage, a significant portion of your payment goes toward interest rather than principal. Add legal fees, inspections, closing costs, property taxes, maintenance, and eventual selling commissions, and short-term ownership can be more expensive than many first-time buyers anticipate.

We often walk clients through this reality using simple projections:

  • Mortgage interest vs. principal breakdown in years one to three

  • Total transaction costs of entering and exiting the market

  • Maintenance allowances and contingency reserves

  • Opportunity cost of tying up down payment capital

If you expect to move within a few years, or if entering the market would leave you with minimal emergency reserves, renting may preserve flexibility rather than weaken your position.

When Buying Makes Sense Financially and Structurally

Buying becomes compelling when your foundation is stable and your time horizon extends beyond short-term fluctuations. Ownership rewards discipline and patience more than timing or speculation.

If you plan to remain in your home for at least five years, your income is stable, and you can maintain healthy liquidity after closing, ownership can provide long-term leverage. Time in the market allows appreciation and principal repayment to compound in your favour.

The First Home Savings Account (FHSA) is also playing a meaningful role for prepared buyers. With up to $8,000 in annual contribution room and tax-deductible contributions that can be withdrawn tax-free for a qualifying purchase, it has become a practical tool for accelerating a down payment strategy. For disciplined savers, that advantage compounds quickly.

Without a sufficient time horizon or financial cushion, ownership becomes more vulnerable to transaction costs, rate changes, and short-term market swings. But when stability is present, buying shifts from being a risk decision to a wealth-building one.

What Costs Do First-Time Buyers Often Underestimate?

Comparing rent to a mortgage payment in isolation is one of the most common financial mistakes we see. Ownership carries additional costs that materially affect affordability.

Beyond your mortgage payment, ownership includes:

  • Property taxes

  • Insurance

  • Maintenance and repairs

  • Utilities

  • Condo fees or special assessments, where applicable

  • Opportunity cost of down payment capital

Renting, while not building equity, offers predictability and reduced exposure to unexpected expenses. The disciplined approach is to stress test the decision:

  • Could you carry the property if rates increased modestly?

  • Would you still feel comfortable if appreciation slowed?

  • Will you maintain reserves of at least 3 to 6 months after closing?

Ownership should feel stable, not tight.

What to Buy in Calgary’s Market?

Once you have determined that buying makes sense structurally, the next question becomes just as important: what are you buying?

In Calgary, land-based properties such as detached and semi-detached homes have historically demonstrated greater long-term resilience than higher-density units. The reason is structural. Land is finite, while condo inventory can expand more quickly, especially during active building cycles.

This does not mean condos are inherently a poor choice. However, buying a condo in Calgary with the expectation that rapid appreciation will quickly allow you to “move up” the property ladder is generally not a reliable strategy.

Property type and supply dynamics matter, and first-time buyers should enter the market with realistic expectations about how different segments tend to perform over time. In other words, if you’re making the decision to buy a condo in Calgary, this should align directly with your long-term goals and lifestyle and not unrealistic financial hopes about how the market will perform. 

How Calgary’s Current Dynamics Are Creating More Opportunity for Buyers

For many potential first-time buyers who felt boxed out of the detached and semi-detached market segments, Calgary’s current supply dynamics are particularly relevant today.

During the peak of the market a few years ago, there were periods where fewer than 30 detached homes were available under $500,000. Today, there are closer to 96 homes in that price range. Increased entry-level inventory creates access that simply did not exist during tighter cycles.

At the same time, government incentives such as GST rebates on qualifying new builds, combined with builder incentives in a more competitive environment, are increasing the appeal of new construction. For some buyers, the decision is no longer rent versus resale. It is rent versus purchasing a brand-new home at a comparable monthly cost.

This combination of stabilized pricing, expanded inventory, and builder competition is creating opportunities for prepared buyers who were previously sidelined by limited options.

Final Thoughts: Readiness Over Pressure

In Calgary, homeownership has long been treated as a milestone. Renting is sometimes viewed as temporary or inferior, and that narrative can quietly influence financial decisions almost as much as market timing.

Buying to avoid embarrassment, meet social expectations, or act out of fear of missing out may feel understandable in the moment, but it rarely produces strong long-term outcomes.

In today’s balanced 2026 market, the rent-versus-buy decision is not about chasing momentum or status. It is about alignment.

With more entry-level inventory, builder incentives, and realistic pricing, there are more opportunities available to first-time buyers. But opportunity still requires discipline. The strongest first-time buyers are not the most aggressive. They are the most prepared.

Renting is not a failure. Buying is not automatically wealth-building. The right move is the one that protects your liquidity, respects your time horizon, and positions you for durable financial progress.

___

If you are currently weighing your options, we would be happy to help you model both paths using your income, savings, and preferred property type so you can move forward with clarity rather than pressure.

Read
Data is supplied by Pillar 9™ MLS® System. Pillar 9™ is the owner of the copyright in its MLS®System. Data is deemed reliable but is not guaranteed accurate by Pillar 9™.
The trademarks MLS®, Multiple Listing Service® and the associated logos are owned by The Canadian Real Estate Association (CREA) and identify the quality of services provided by real estate professionals who are members of CREA. Used under license.